Creating a robust and legally compliant certificate of insurance is paramount for businesses and individuals alike. It serves as a crucial document proving that you have adequate coverage to protect against potential financial losses due to unforeseen events. A well-designed and accurately filled certificate of insurance template is an investment in peace of mind and can significantly reduce risk. This article will delve into the essential components of a certificate of insurance, exploring its purpose, key elements, and best practices for ensuring its effectiveness. Certificate Of Insurance Template is more than just a form; it’s a vital tool for safeguarding your assets and operations.
The primary function of a certificate of insurance is to demonstrate that you have sufficient financial protection to cover potential liabilities. It’s a standardized document that verifies the financial strength of an insurance provider and provides assurance to your clients, partners, and stakeholders. Without a properly drafted and maintained certificate of insurance, businesses can face significant legal and financial repercussions if a claim arises. It’s a cornerstone of responsible risk management. Understanding the nuances of different types of insurance and the specific requirements of each can further enhance the value and effectiveness of your certificate of insurance.
Understanding the Purpose of a Certificate of Insurance
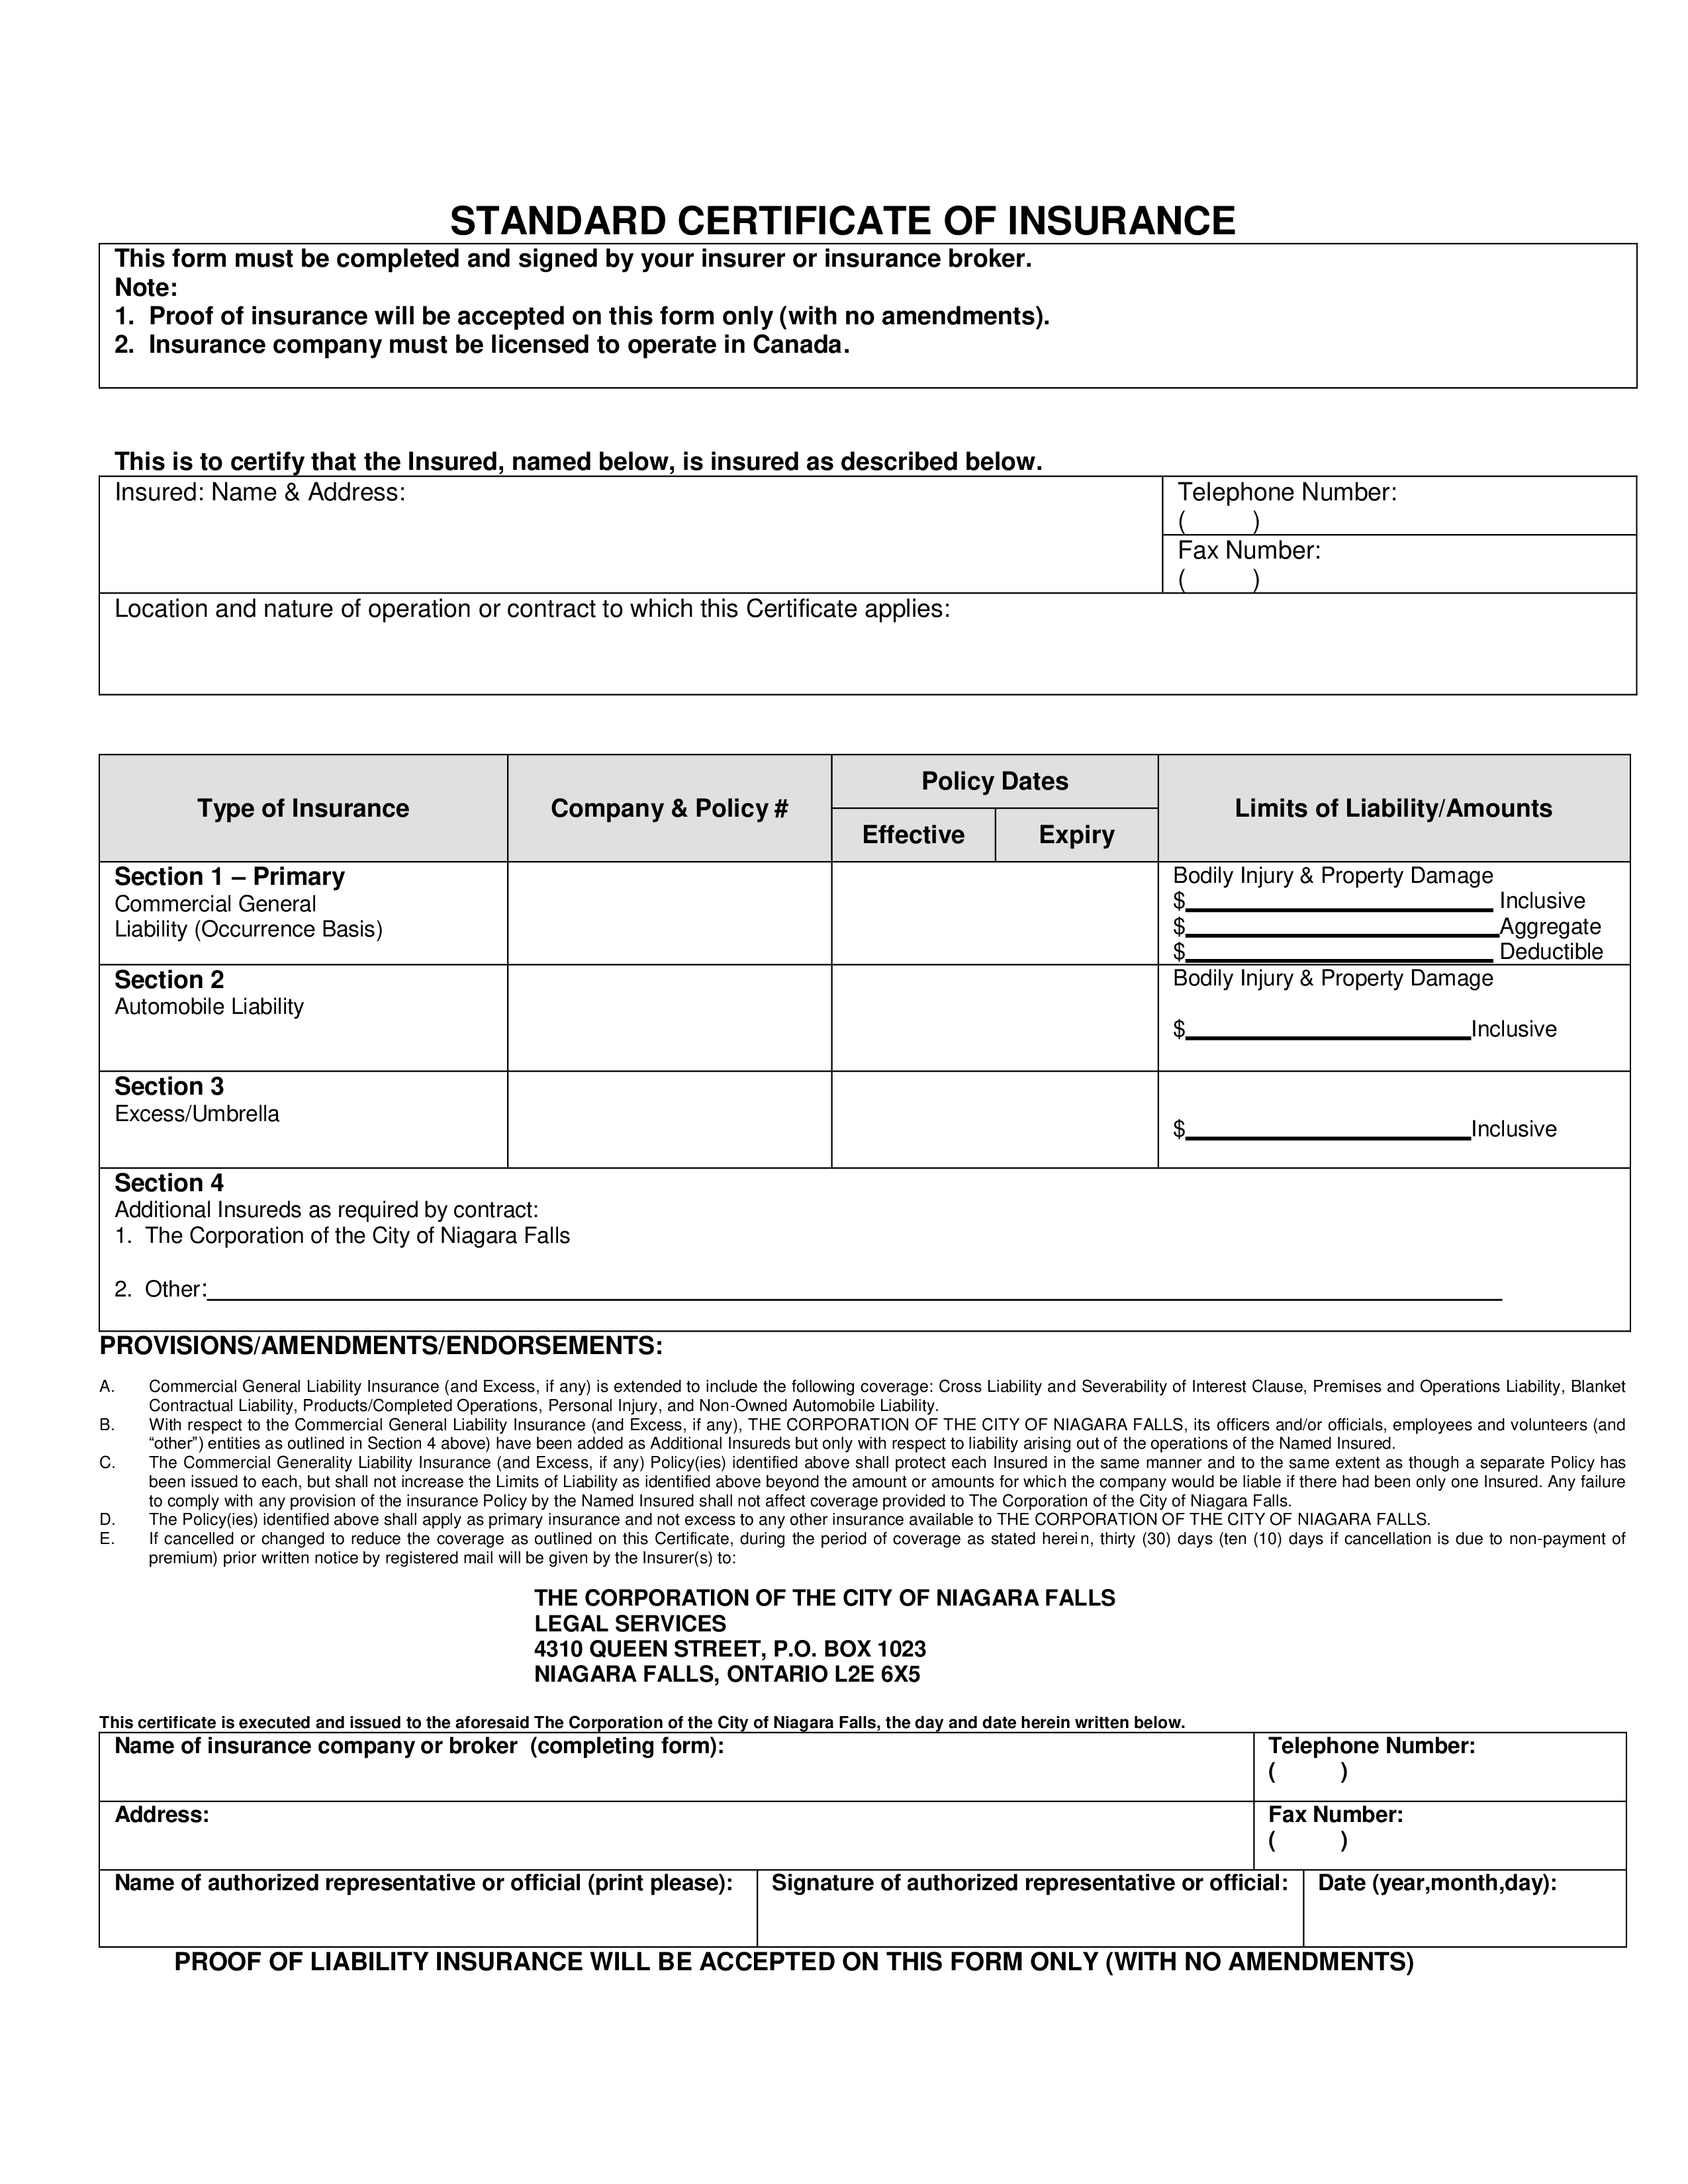
A certificate of insurance, also known as an insurance certificate, is a formal document that certifies that an insured party has sufficient financial protection to cover potential losses arising from a specific event or risk. It’s not simply a copy of your policy; it’s a legally binding record of your coverage. The purpose is to provide a clear and verifiable record of your insurance coverage, allowing for easy verification by your clients, partners, and insurers. The template itself is designed to be easily adaptable to various types of insurance policies, ensuring consistent and accurate documentation. The specific requirements vary depending on the type of insurance, but the core principles remain the same.
The certificate of insurance is essential for several reasons. Firstly, it’s a critical tool for verifying the financial stability of your business. Clients and lenders routinely require this documentation to assess risk. Secondly, it’s vital for regulatory compliance, particularly in industries like construction, transportation, and healthcare. Thirdly, it provides a clear record of your coverage, simplifying claims processes and reducing disputes. Finally, it demonstrates your commitment to protecting your assets and ensuring business continuity.

Key Components of a Certificate of Insurance Template
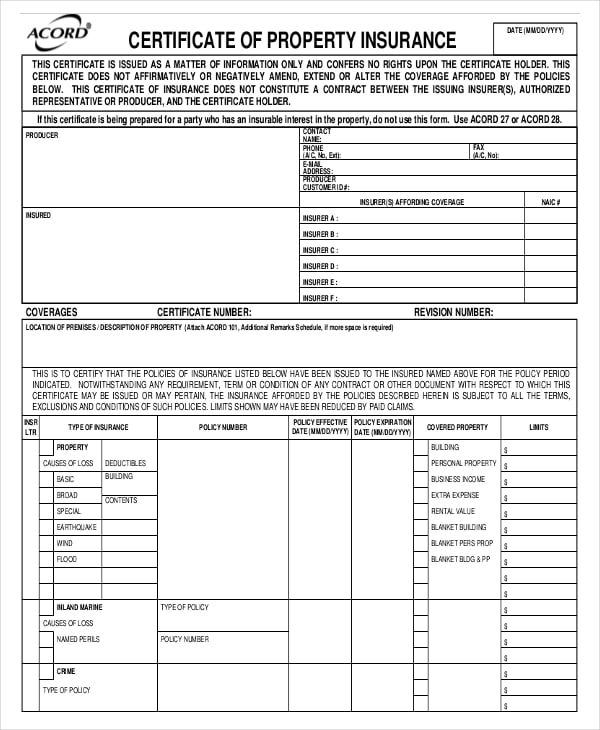
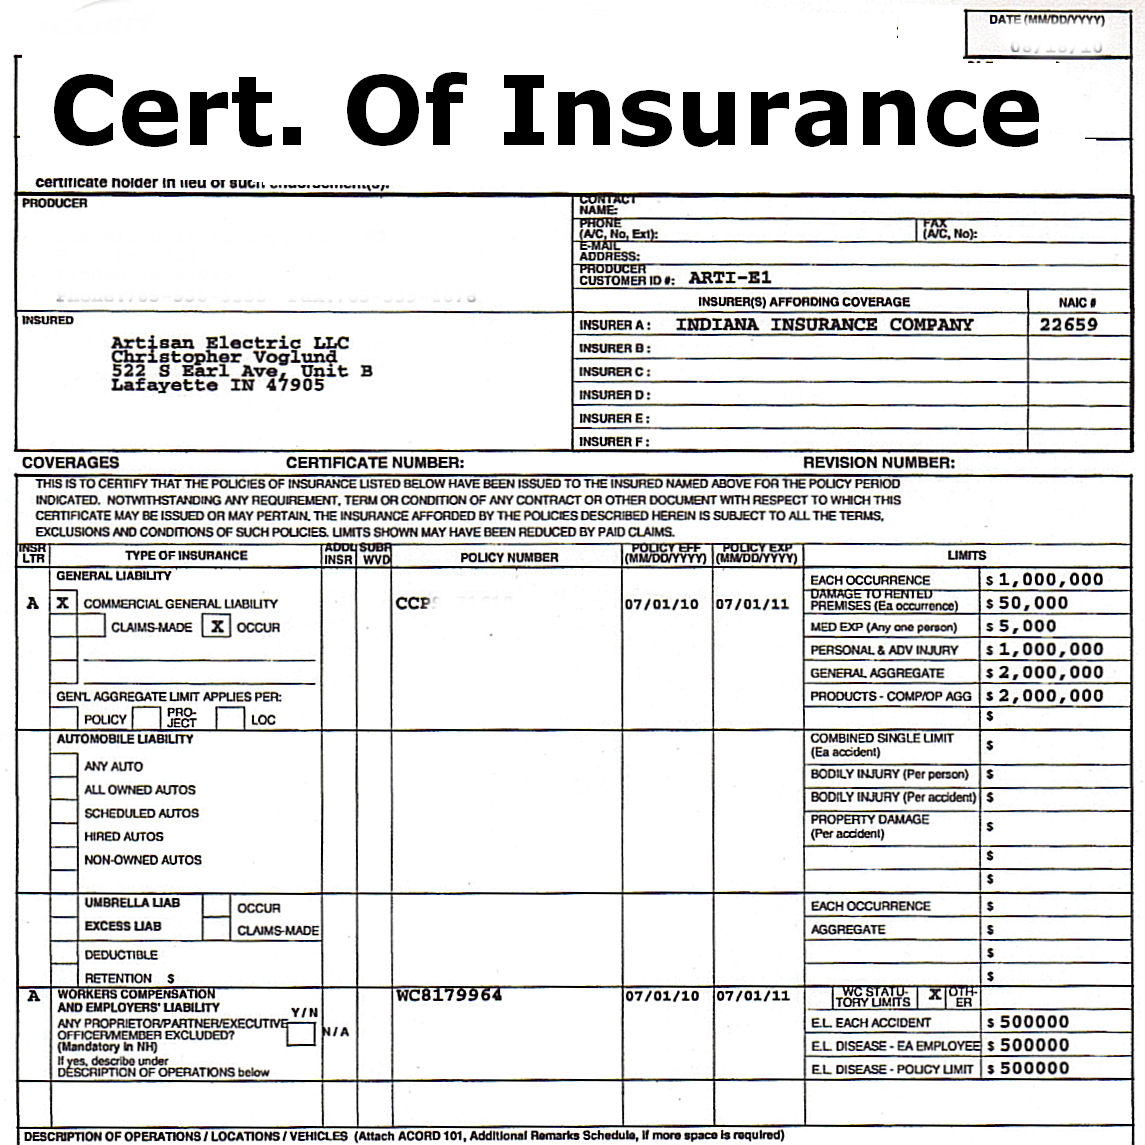
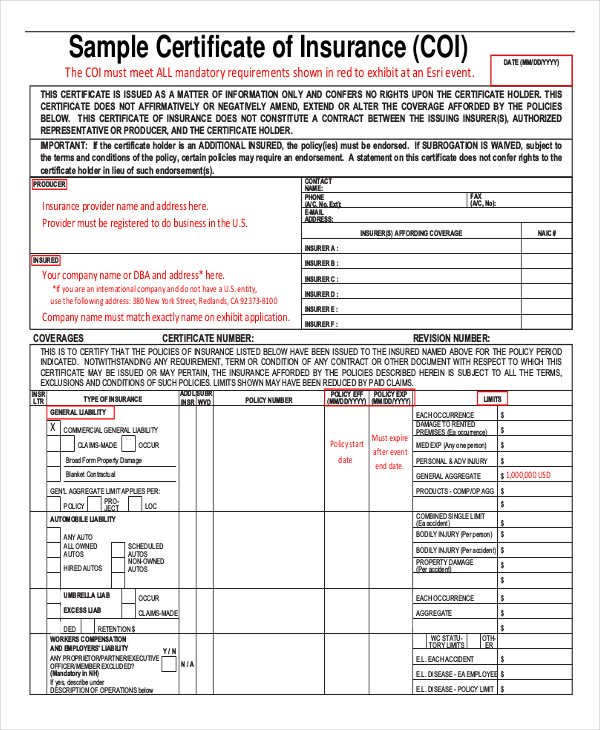
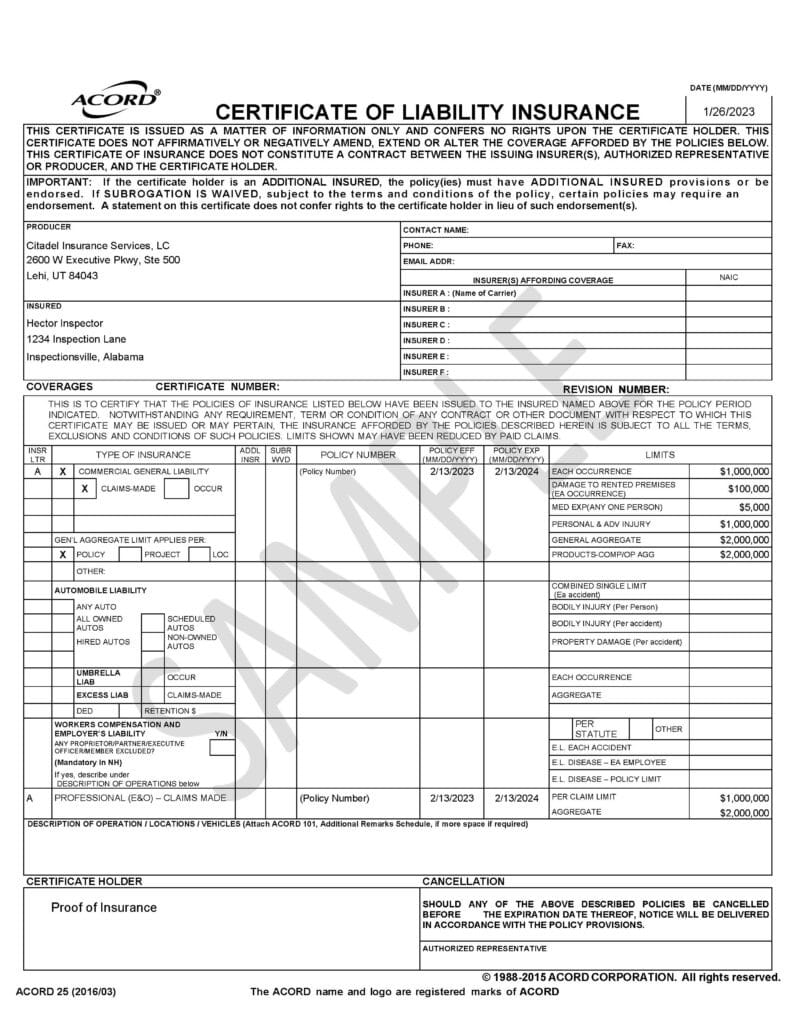
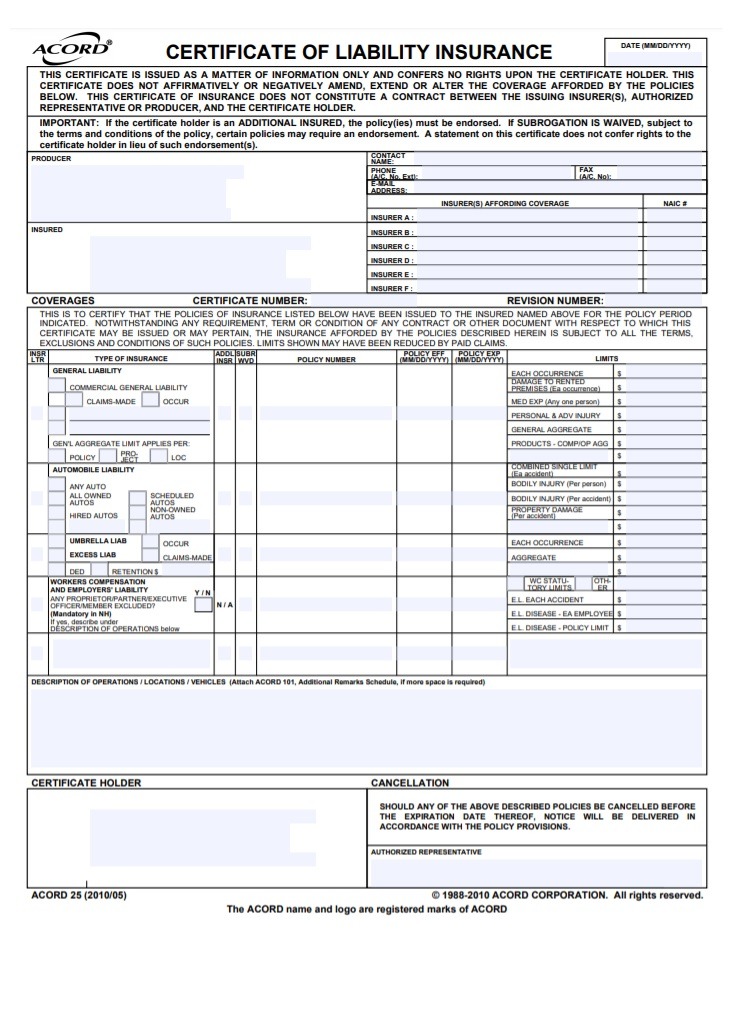
A comprehensive certificate of insurance typically includes several key components. These elements are carefully structured to provide a clear and concise overview of your coverage. The template often includes sections dedicated to:

- Policy Number: A unique identifier assigned to your insurance policy.
- Policyholder Information: The name, address, and contact details of the insured.
- Insured Information: Details about the insured’s business or individual, including their legal entity (e.g., sole proprietorship, corporation).
- Covered Risks: A detailed list of the specific risks covered by the policy. This is a crucial section, and it’s important to clearly define what is and isn’t covered.
- Coverage Limits: The maximum amount the insurance company will pay for a covered loss.
- Deductibles: The amount the insured must pay out-of-pocket before the insurance coverage kicks in.
- Exclusions: A list of events or circumstances that are not covered by the policy.
- Signature and Date: A signature from the insured and a date indicating when the certificate was issued.
Section 2: Liability Coverage – Protecting Against Financial Loss
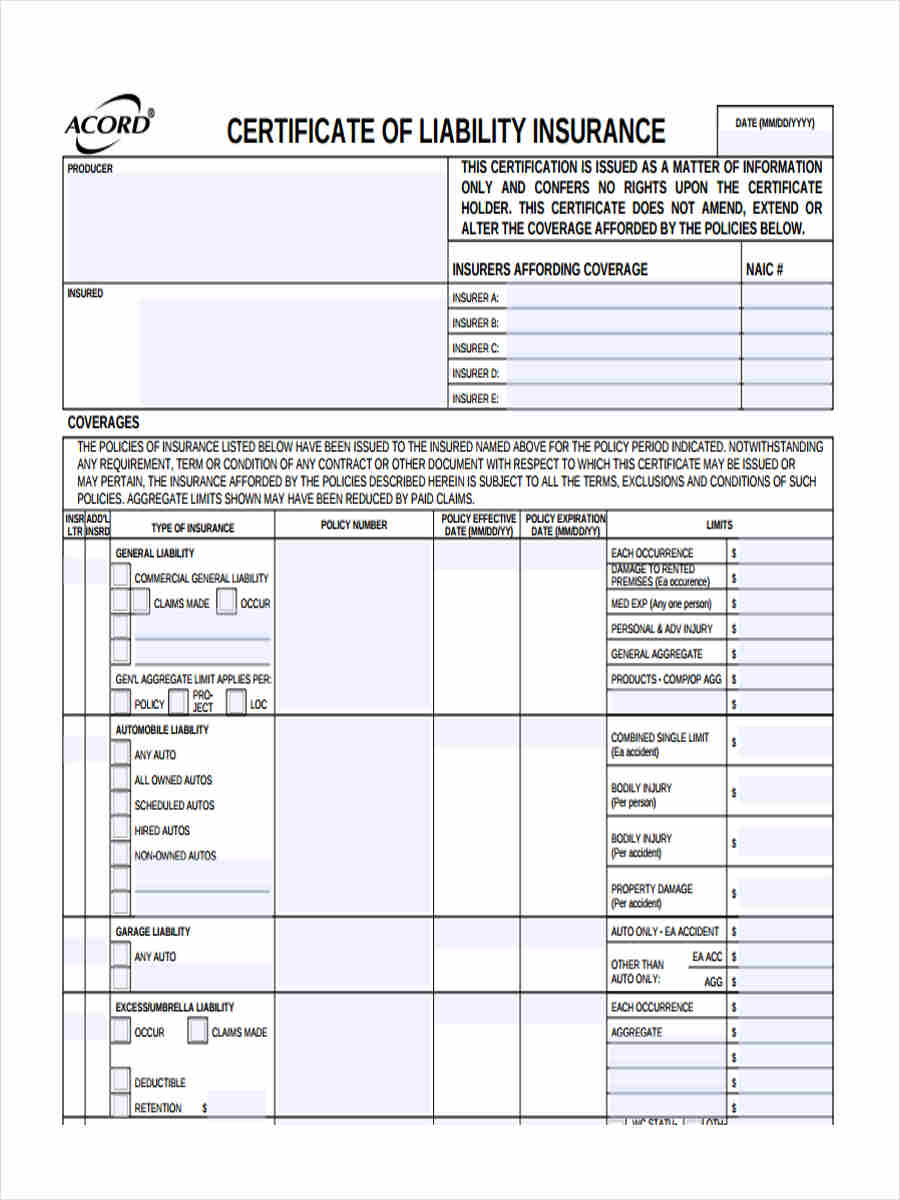
A significant portion of a certificate of insurance focuses on liability coverage. This type of insurance protects against financial losses arising from claims of negligence, errors, or damages caused to others. It’s often a critical component for businesses that provide services to others, such as contractors, professionals, or retailers. The liability coverage typically includes:

- Bodily Injury Liability: Covers medical expenses and legal costs resulting from injuries sustained by third parties.
- Property Damage Liability: Covers damage to the insured’s property caused by third parties.
- Product Liability Liability: Covers claims arising from defective products causing injury or damage.
- General Liability: Provides protection against claims of bodily injury or property damage caused by the insured’s operations.
It’s important to carefully review the specific terms and conditions of your liability coverage to ensure it adequately protects your business. Consulting with an insurance professional is highly recommended to determine the appropriate level of liability coverage for your specific needs.
Section 3: Business Interruption Coverage – Maintaining Operations
Beyond liability, business interruption coverage is increasingly important for businesses that rely on their operations for income. This type of coverage protects against losses incurred due to a disruption in business operations caused by a covered event, such as fire, flood, or other covered perils. It helps to mitigate the financial impact of unexpected disruptions, allowing businesses to continue operating and maintain their revenue streams. Key aspects of business interruption coverage include:
- Loss of Profits: Covers lost profits due to the interruption of business operations.
- Replacement Costs: Covers the costs of replacing lost equipment, inventory, and other assets.
- Business Expenses: Covers expenses incurred to resume business operations, such as temporary relocation costs.
Section 4: Commercial Property Insurance – Safeguarding Your Assets
Commercial property insurance protects the physical assets of your business, including buildings, equipment, inventory, and other property. It’s a fundamental component of risk management for businesses operating in physical environments. Common types of commercial property insurance include:
- Business Property Insurance: Covers damage to buildings, equipment, and inventory.
- Casualty Insurance: Covers damage to buildings and equipment caused by fire, theft, vandalism, and other covered perils.
- Builder’s Risk Insurance: Protects against damage to buildings and equipment caused by events occurring during the construction process.
Section 5: Important Considerations and Best Practices
- Review Your Policy Carefully: Thoroughly read and understand the terms and conditions of your certificate of insurance policy.
- Update Your Policy Regularly: Review your policy annually to ensure it still meets your current needs and risk profile.
- Maintain Accurate Records: Keep accurate records of your insurance coverage, including policy numbers, coverage limits, and deductibles.
- Notify Your Insurer Promptly: Notify your insurer of any changes to your business or operations that could affect your risk profile.
- Understand Exclusions: Be aware of the exclusions in your policy and how they might affect your coverage.
Conclusion
A well-crafted and properly executed certificate of insurance is an indispensable tool for protecting your business and ensuring financial stability. It’s a critical document that demonstrates your commitment to risk management and provides assurance to your clients, partners, and stakeholders. By understanding the key components of a certificate of insurance and adhering to best practices, you can significantly reduce your risk exposure and safeguard your assets. Investing in a robust insurance strategy is an investment in the long-term success of your business. Certificate Of Insurance Template is a vital component of this strategy.
Conclusion
The certificate of insurance serves as a cornerstone of responsible risk management, providing a verifiable record of financial protection and assurance to various stakeholders. Its importance extends beyond simple compliance, directly impacting business operations, reputation, and ultimately, profitability. A comprehensive and meticulously maintained certificate of insurance is not merely a formality; it’s a proactive measure safeguarding against potential financial losses and fostering a stable and secure business environment. Continued diligence in reviewing and updating policies is essential to maintain optimal risk mitigation strategies.

Related posts of "Certificate Of Insurance Template"
